

Checkbook - Account Tracker
3.6

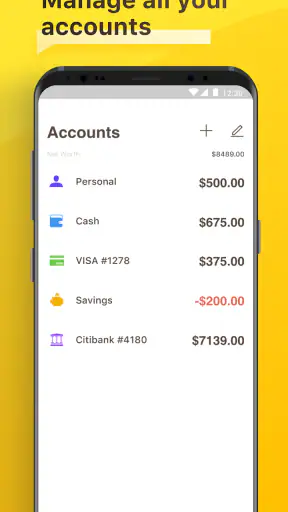
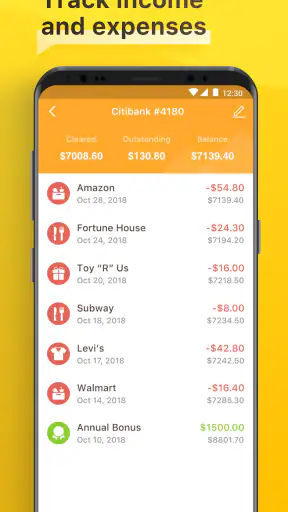
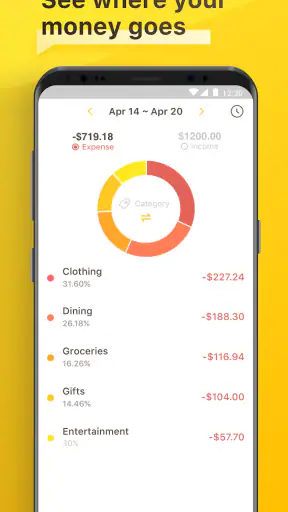
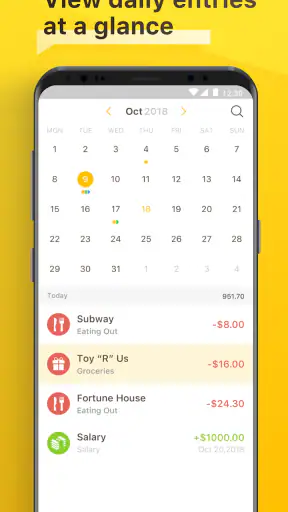
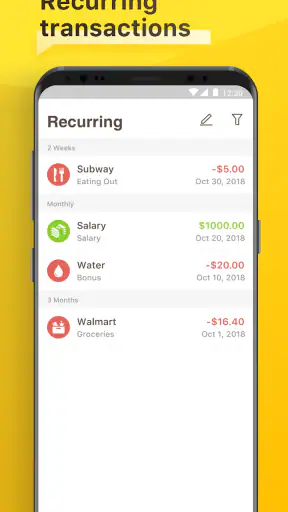
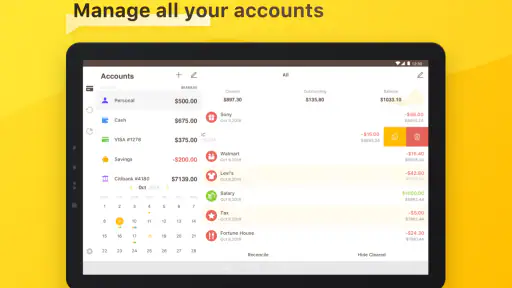
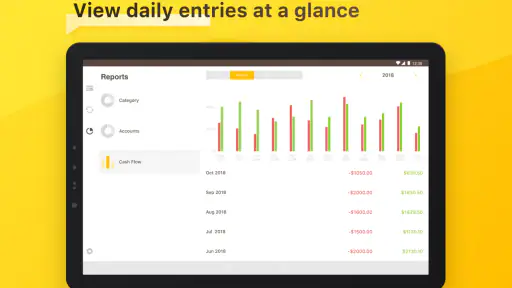
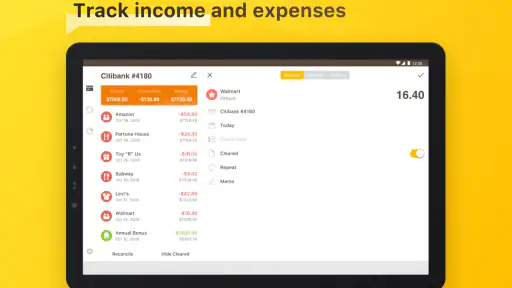
I like finance apps that stay out of the way. When I am recording a coffee, a bill, or a transfer, I do not want a complicated budgeting system asking me to build a financial plan first. Checkbook - Account Tracker takes that simpler route: it is a digital register for recording money coming in and going out, much like the paper checkbook many people used before mobile banking became normal.
That narrow purpose is both its appeal and its main limitation. In my experience, this is most useful when I want a clear running balance for one account and prefer entering transactions myself. It is less convincing if I expect automatic bank connections, detailed spending analysis, or a complete household-finance dashboard. The app is free to install, is rated for Everyone, and comes from TinyWork Apps. Its current version is 2.1.2, and it supports devices running Android 7.0 or later.
How the current version feels in everyday use
The first thing I noticed is that the app is built around the register rather than around charts or financial goals. That makes the basic workflow easy to understand: record a transaction, check the balance, and use the list as a practical history of activity. It feels closer to replacing a small notebook than to adopting a full personal-finance platform.
That simplicity works well for people who already know how they want to track an account. I can imagine using it for a checking account, a cash envelope, a shared household expense pool, or an account where I want to keep a separate manual record. The app does not need to become the center of my financial life to be useful. It can serve as one focused ledger.
A realistic example is payday. I might enter the deposit, then add rent, utilities, groceries, transport, and smaller card payments as they happen. At the end of the week, the running balance gives me a quick reality check. The important habit is entering transactions immediately. If I wait several days and try to reconstruct everything from memory, a manual register becomes much less reliable.
That is the key trade-off: the app gives me control, but it also gives me responsibility. A bank-connected tool can import activity while I am busy. This one is better suited to someone who wants to confirm each entry personally. For privacy-conscious users, that manual approach may feel reassuring. For users who routinely forget to record purchases, it can become an extra chore.
A good fit for deliberate, manual tracking
I would recommend it first to someone replacing a paper checkbook register. The mental model is familiar, and the app does not force a person to learn a large collection of financial terms or planning screens. It also makes sense for users who want to monitor a single account without mixing that task with investments, credit scores, subscriptions, and long-term planning.
It can also be useful for people who keep a separate record of cash spending. Cash is easy to lose track of because there is no automatic transaction feed. Entering each withdrawal and purchase in a register can make the remaining amount visible. The same method works for a small project fund or a travel budget, provided the user is comfortable maintaining the entries by hand.
One practical tip is to treat pending card purchases carefully. If I record a purchase before it fully clears, I need a consistent personal rule: either include it immediately as an expected reduction or wait until it appears in the account. Mixing those approaches can make the balance look correct one day and misleading the next. A manual register is strongest when the user follows one repeatable routine.
Where it differs from modern banking apps
My banking app is better when I need official transaction status, current account information, or confirmation that a payment actually cleared. A budgeting app is usually better when I want category totals, spending trends, recurring bills, or a combined view of several accounts. A spreadsheet is more flexible when I need custom formulas and reports.
This app occupies a smaller space between those options. It is not trying to replace the bank’s source of truth, and I would not use it as the only record for important financial decisions. Instead, it offers a controlled personal ledger. That can be an advantage when I want a simple workflow, but it also means I should compare the register with official statements regularly.
For someone who wants automatic synchronization, this is probably the wrong choice. Manual entry is not a hidden benefit for everyone. It is a deliberate design direction, and users who want effortless tracking may find it frustrating. Likewise, anyone looking for tax preparation, debt payoff planning, investment monitoring, or advanced household reporting should look toward a more specialized finance product.
What the version and history suggest
The app was released on July 24, 2015, and the current version is 2.1.2. That history helps explain its straightforward identity. It feels like a focused utility that has remained centered on the register concept instead of expanding into every possible financial feature.
I would be careful about interpreting a version number as a promise of a particular roadmap. The useful evidence today is that the app remains available as a focused account tracker, supports Android 7.0 and later, and has a sizable user base: it has passed 100 thousand installs. Its average rating is 3.6 from around 9 thousand ratings, with more than 4 thousand written reviews. Those figures suggest a product that works for a meaningful group of people but is not universally satisfying.
For existing users, the main benefit of staying with it is familiarity. A long-used register contains personal history and established habits, so a simple update is less disruptive than moving to a completely different finance system. If the current workflow already matches the way I think about money, there is value in not replacing it just because newer apps look more polished.
At the same time, long-term users should periodically check whether the app still matches their needs. A register that was perfect when I tracked one account may feel too limited after adding a second bank, shared expenses, subscriptions, or savings goals. The question is not whether the app is old or simple; it is whether the simple model still prevents mistakes in my current routine.
Small habits that make the register more dependable
The best improvement does not come from a setting. It comes from the way I use the app. I would enter transactions at the moment I make them, use clear descriptions, and reconcile the displayed balance with the bank statement on a regular schedule. That turns the register into a useful checkpoint rather than a vague memory aid.
I would also avoid using one account as a catch-all for unrelated money. If I mix personal spending, cash withdrawals, reimbursements, and a temporary trip fund without a consistent method, the transaction list becomes harder to interpret. A focused ledger is easier to trust when every entry belongs to the same financial purpose.
Another useful approach is to record transfers deliberately. Moving money between accounts is not the same as spending it, and treating every movement as an expense can distort the picture. Before entering a transfer, I would decide whether the app is being used to track one account or both sides of the movement. That distinction matters more in a manual tool because the accuracy of the result depends on the user’s choices.
I would keep the app as a companion to official records rather than as a replacement for them. If the balance differs, the bank statement should win, and the register should be corrected. This is not a criticism unique to this product; it is the natural consequence of using a manually maintained account tracker. The app can organize my record, but it cannot know about a transaction I never enter.
Limitations I would want to know before installing
The biggest limitation is the amount of attention required. Automatic import has become normal in many finance apps, so some users may find manual recording dated or inconvenient. If I make frequent small purchases, the number of entries can become tiring. The app is most comfortable for people who value control more than automation.
The second limitation is scope. A register can show what happened, but it does not automatically explain why spending changed or help me decide what to do next. If I want visual reports, category comparisons, bill reminders, shared planning, or a broad financial overview, I would need another tool or a different app entirely.
I would also think carefully before relying on it for multiple accounts. A simple tracker can still be useful across separate ledgers, but the more accounts I manage, the more opportunities there are for missed entries, duplicated transfers, and confusing balances. Someone managing a family’s complete finances may outgrow this approach quickly.
There is a free entry point, while in-app purchases range from $0.99 to $19.99 per item. I would consider the purchase screen part of the decision rather than assuming every function is included at no cost. Before depending on a paid option, I would check exactly which part of the workflow it changes and whether that improvement solves a problem I actually have.
Who should choose it, and who should skip it
I think it is a sensible choice for a person who wants a digital checkbook register, prefers manual control, and needs something less elaborate than a full budgeting suite. It may also suit someone moving away from paper records but not ready for automatic account aggregation. The Everyone age rating makes it broadly accessible, and the Android requirement covers many older devices.
I would skip it if my first question is whether it can connect to my bank and update itself. I would also look elsewhere if I need sophisticated reports, investment tools, debt planning, or a shared system with several people entering transactions. In those cases, the simplicity that makes this app approachable becomes a real constraint.
My recommendation is therefore conditional but positive. If I wanted a clean, manual ledger for a focused account, I would give it a try. I would not install it expecting a modern financial command center. Its real strength is dependable simplicity, provided I am willing to maintain the record.
What I would watch after the current release
For future updates, I would pay attention to whether the app continues to make manual entry quick and clear, especially on older supported devices. I would also want the register experience to remain stable as the transaction history grows. Those details matter more here than adding flashy financial features.
Existing users should watch how well their established records and habits carry forward after updates, while new users should judge the app after a realistic trial period rather than after entering only a few transactions. The important test is whether the balance stays trustworthy during an ordinary month of deposits, purchases, withdrawals, and corrections.
After using it as a focused account tracker, I see Checkbook - Account Tracker as a practical utility rather than an all-purpose finance solution. TinyWork Apps has kept the idea clear: replace the paper register with a mobile one. That will feel refreshingly manageable to the right person and noticeably limited to everyone else. If your goal is to record transactions carefully and see a running balance without financial clutter, it is worth considering. If your goal is automation and analysis, your usual banking or budgeting alternative will probably serve you better.
3.6
4.29K Reviews
Pros
- Simple interface makes daily income and expense tracking quick.
- Supports multiple accounts for separating personal and business finances.
- Recurring transactions reduce repetitive data entry.
- Budget and balance views help monitor spending habits.
- Useful reports provide a clearer picture of cash flow over time.
Cons
- Some advanced features may require an in-app purchase.
- Manual entry can feel tedious for users expecting bank synchronization.
- Limited sharing options may not suit families or joint account holders.
- The app may take time to set up if you have many past transactions.
- Backup and export features may vary depending on the device or plan.


